Splitero vs Point vs Unlock vs Hometap: 2026 CA HEI Comparison
- Home Equity Investment
- HEI
Which California Home Equity Investment Provider Is Best?
Splitero is best for matching your existing first mortgage term (up to 30 years) with credit scores down to 500. Point excels for non-owner-occupied and 1–4 unit properties. Unlock is ideal for homeowners wanting partial equity buybacks over a 10-year term, while Hometap suits rapid automated underwriting with transparent annual appreciation caps.
Home Equity Investment California: Point vs. Unlock vs. Hometap vs. Splitero
A California Home Equity Investment (HEI)—also known as a Home Equity Sharing Agreement—allows residential property owners to convert home equity into immediate, lump-sum liquidity without monthly payments, interest charges, or refinancing senior mortgages. In exchange for capital today, the equity provider purchases an option on a contracted share of your home's future value, realized at settlement or term maturity.
For California homeowners in high-appreciation markets like Los Angeles, Orange County, Silicon Valley, and San Diego, an HEI unlocks up to $600,000 while preserving existing 2.5%–4.0% first-lien fixed mortgages.
Check Your California No-Monthly-Payment Equity Access
Access $30,000 to $600,000 from your primary or 1–4 unit property. Zero monthly debt service, no rigid DTI caps, and credit scores down to 500 accepted.
Eligibility Credit Score Tiers:
500 – 579: HEI Eligible (Asset & Equity-Based)
580 – 659: Standard HEI & Expanded Criteria
660 – 719: Prime HEI & Second Mortgage Options
720+: HELOC, HEI & Cash-Out Refinance
Key Features of California Equity Sharing Agreements
Zero Monthly Debt Service: No principal or interest payments required during the 10- to 30-year term.
Senior Lien Preservation: Keep existing low-rate primary financing untouched; the HEI files as a junior Deed of Trust.
Flexible Credit Underwriting: Approvals down to a 500 FICO score with no conventional debt-to-income (DTI) caps.
No Income Verification Hurdles: Qualification is asset-based, anchored in property appraisal, CLTV thresholds, and title equity.
Downside Market Protection: If California real estate values decline, the equity provider shares proportionately in the loss upon final settlement.
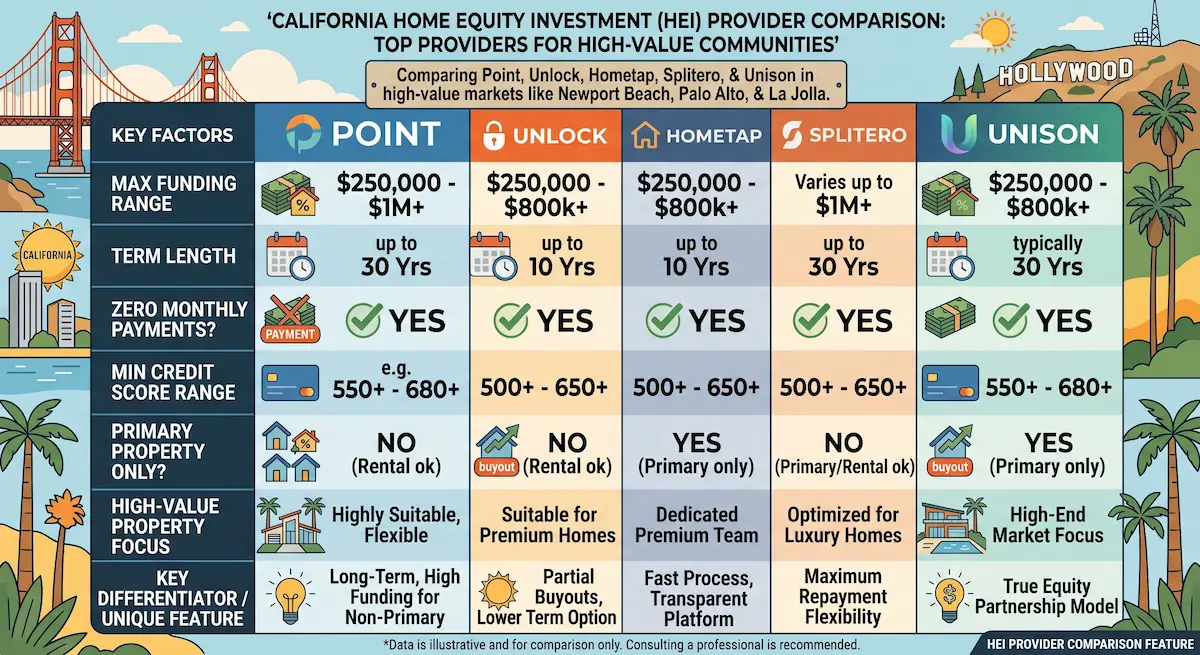
California HEI Provider Comparison Matrix (2026 Guidelines)
In-Depth Analysis of Leading California Shared Equity Providers
1. Splitero
Splitero is purpose-built for California homeowners seeking debt consolidation, cash flow relief, or property renovation capital without taking on monthly debt. Its flagship Maturity Match™ ensures your equity agreement timeline matches your remaining primary mortgage term rather than forcing an early 10-year balloon refinancing event.
Maximum Investment: Up to $600,000 or 25% of appraised value.
Combined LTV Limit: Up to 80%–85% CLTV.
Credit Guidelines: 500 minimum FICO. No strict income caps.
Settlement Flexibility: Repay anytime via refinance, cash, or sale with zero prepayment penalties.
California Footprint: Fast closings across Los Angeles, Orange County, San Diego, and Riverside.
2. Point
Point offers broad flexibility across single-family homes, condominiums, and 1–4 unit residential properties throughout the San Francisco Bay Area, Silicon Valley, and Southern California coastal markets.
Maximum Investment: Up to $600,000 (or 20% of property value).
Term Duration: 30 years (maximum runway for long-term holds).
Underwriting Standards: 500 minimum FICO; accommodates self-employed, 1099, and retired homeowners.
Fee Structure: 3.9% to 5.9% deducted directly from proceeds at closing.
3. Unlock Technologies
Unlock is designed for homeowners wanting gradual exit strategies. While most HEI products require a single lump-sum payoff at the end, Unlock allows California owners to buy back equity in partial installments over a 10-year term.
Maximum Investment: Up to $500,000 (up to 19.9% of home value).
Term Duration: 10 years.
Minimum FICO: 500.
Best For: Homeowners anticipating liquidity events who want to buy out the investor early in increments.
4. Hometap
Hometap provides straightforward 10-year shared equity contracts with fixed percentage buyback equations and transparent caps on total annual investor appreciation.
Maximum Investment: Up to $600,000 (up to 25% of home value).
Term Duration: 10 years.
Minimum FICO: 585.
Fee Structure: 4.5% origination fee deducted from closing escrow.
How HEI Settlement & Buyouts Work
Homeowners retain 100% of property title and deed ownership. The HEI provider places a junior lien (Deed of Trust) on the home. Settlement occurs when the homeowner chooses to exit, triggered by one of three mechanisms:
Cash Buyout: Pay the contracted repurchase balance using cash or liquid assets without selling the property.
Mortgage Refinance: Secure a traditional cash-out refinance, standalone wholesale second mortgage, or HELOC to pay out the investor.
Property Sale: Sell the property on the open market, where the investor's contracted percentage is disbursed directly from escrow proceeds.
HEI vs. HELOC vs. Wholesale Second Mortgage
California Equity Guidance with S.O.S. Loans
Trading home appreciation for immediate capital is a major financial decision. S.O.S. Loans, Inc. (NMLS #2222125) provides direct wholesale access to Splitero HEI products alongside California HELOCs and fixed second mortgages, giving you an unbiased side-by-side cost projection before you commit.
Request your California home equity analysis or call (800) 503-6648 ext 2 to review your options with Frank Stiebel.