Mutual of Omaha vs. Longbridge: California Jumbo Reverse Mortgage Comparison
- Jumbo Reverse Mortgage
California Jumbo Reverse Mortgage Guide | 2026
Mutual of Omaha vs. Longbridge: California Jumbo Reverse Mortgage Comparison
For California homeowners with high-value properties, a jumbo reverse mortgage may provide access to substantially more home equity than a traditional FHA-insured HECM. Proprietary reverse mortgage programs are designed for qualifying homeowners whose property value or borrowing needs may exceed standard HECM limits.
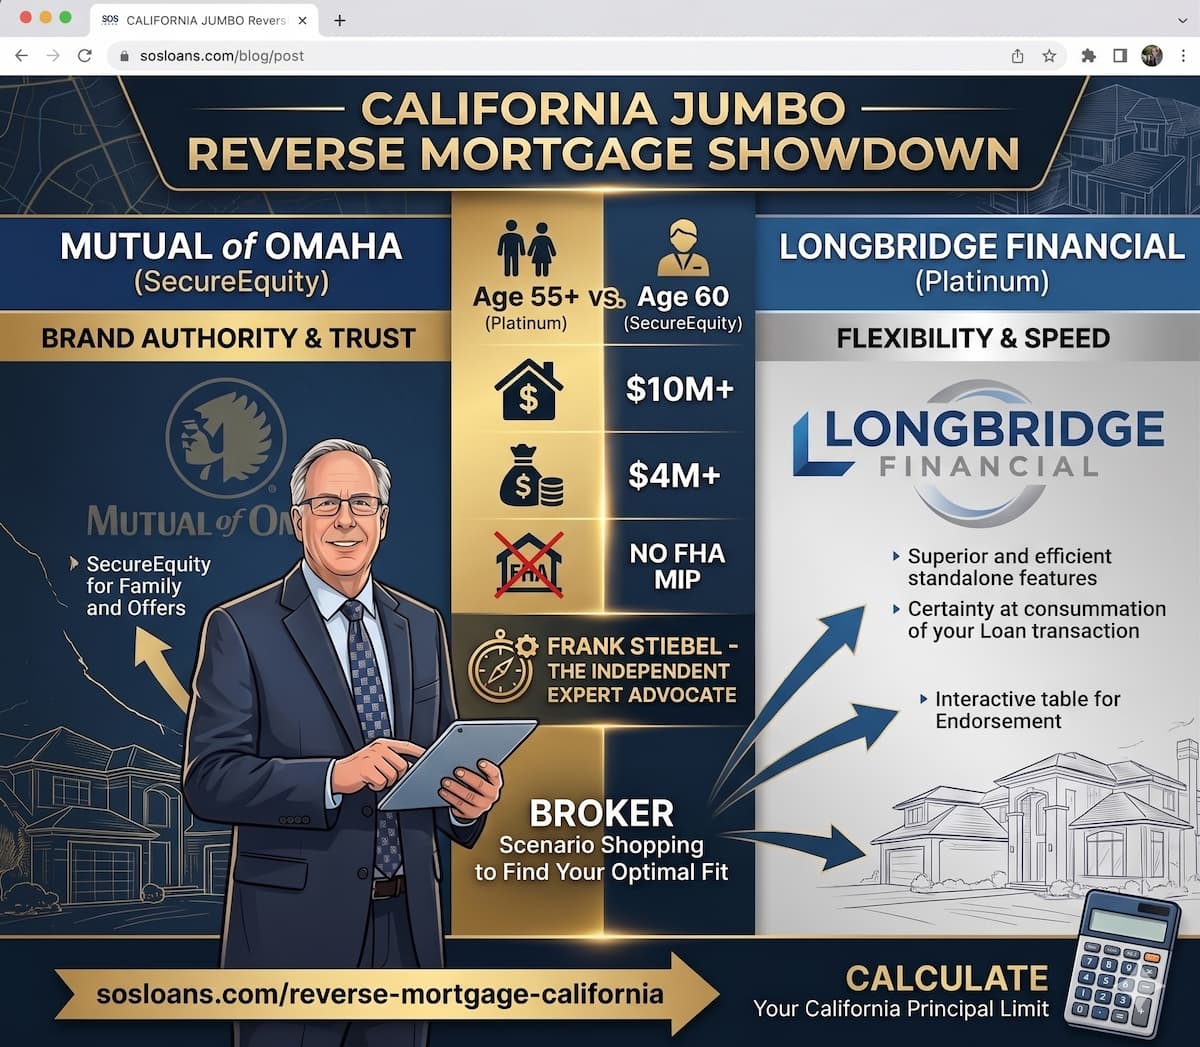
Two programs California homeowners may encounter are Mutual of Omaha SecureEquity and Longbridge Financial Platinum. This guide compares the two programs, along with Finance of America HomeSafe Second, and explains the factors that can affect eligibility, available proceeds, property requirements, lien structure, and underwriting.
Program availability, eligibility requirements, loan amounts, pricing, property guidelines, and underwriting criteria can change. Actual terms are determined by the applicable lender and program guidelines for the individual borrower and property.
Which Is Better: Mutual of Omaha or Longbridge?
There is no single best proprietary reverse mortgage for every California homeowner. Mutual of Omaha, Longbridge Financial, Finance of America, and other providers can have different eligibility requirements, property guidelines, loan structures, and underwriting criteria. The better fit depends on the borrower's age, property value, existing mortgage, property type, financial profile, and goals.
Estimate My Potential Proceeds →
California Jumbo Reverse Mortgage Programs at a Glance
The following comparison summarizes several characteristics that may be relevant when evaluating proprietary jumbo reverse mortgage programs in California. Because lender guidelines and pricing can change, use the table as a starting point rather than a guarantee of eligibility or proceeds.
Program Feature | Mutual of Omaha | Longbridge Financial | Finance of America |
|---|---|---|---|
Lien Position | Generally structured as a first-lien proprietary reverse mortgage. | Generally structured as a first-lien proprietary reverse mortgage. | A second-lien structure designed for qualifying borrowers who may want to preserve an existing first mortgage. |
Property Value / Loan Size | Designed for qualifying higher-value properties. Available loan amounts depend on current program guidelines, borrower age, property value, and other factors. | Designed for qualifying higher-value properties. Available loan amounts depend on current program guidelines, borrower age, property value, and other factors. | Designed as a proprietary second-lien option for qualifying high-value primary residences. |
Minimum Age | Subject to current program guidelines. | Subject to current program guidelines. | Subject to current program guidelines. |
Property Types | Eligible property types depend on current lender requirements and property review. | Eligible property types depend on current lender requirements and property review. | Primarily intended for qualifying owner-occupied properties meeting program requirements. |
Existing Mortgage | Existing liens generally must be addressed as part of the transaction. | Existing liens generally must be addressed as part of the transaction. | The second-lien structure may allow a qualifying borrower to retain an existing first mortgage. |
FHA Mortgage Insurance | Proprietary program; FHA HECM mortgage insurance requirements do not apply in the same way as they do to a HECM. | Proprietary program; FHA HECM mortgage insurance requirements do not apply in the same way as they do to a HECM. | Proprietary second-lien structure rather than an FHA-insured HECM. |
What Is a Jumbo Reverse Mortgage in California?
A jumbo reverse mortgage in California is a proprietary reverse mortgage designed for qualifying homeowners with higher-value properties or borrowing needs that may exceed the limits of a traditional FHA-insured Home Equity Conversion Mortgage, commonly called a HECM.
Unlike a HECM, proprietary programs are not FHA-insured. They are offered under individual lender or investor guidelines, which means program availability, maximum proceeds, property eligibility, interest rates, fees, and underwriting can differ significantly.
For California homeowners with substantial equity, the important question is usually not simply how much the property is worth. It is how the specific lender calculates available proceeds after considering the homeowner's age, property value, existing liens, interest rate, property characteristics, and financial assessment.
Mutual of Omaha SecureEquity
Mutual of Omaha's SecureEquity program is a proprietary reverse mortgage option intended for qualifying homeowners with higher-value properties. The program can be relevant when a homeowner's borrowing needs or property value exceed what may be practical under a standard HECM.
Important factors to evaluate include the current age requirements, property eligibility, available proceeds, interest rate structure, existing mortgage payoff requirements, and the lender's financial assessment criteria.
Longbridge Platinum
Longbridge Financial's Platinum program is another proprietary reverse mortgage option that can be relevant to California homeowners with higher-value properties.
The important comparison points include current borrower age requirements, property eligibility, maximum available proceeds, rate structure, existing lien requirements, and how the lender evaluates income and assets.
Because proprietary reverse mortgage guidelines can differ from one lender to another, a borrower who does not fit one program exactly may still have another option worth evaluating.
Mutual of Omaha vs. Longbridge: Key Differences
Mutual of Omaha and Longbridge may both be considered for a California jumbo reverse mortgage, but the programs should not be treated as interchangeable.
Property
Compare eligible property types, appraisal requirements, property value limits, and any restrictions affecting luxury homes, condominiums, PUDs, or other property types.
Borrower
Compare age requirements, financial assessment, income documentation, assets, credit considerations, and other underwriting factors.
Loan Structure
Compare first-lien requirements, existing mortgage payoff, available proceeds, fixed-rate or adjustable structures, and how funds can be accessed.
Finance of America vs. Longbridge Financial
Homeowners comparing proprietary reverse mortgage options may also encounter Finance of America and Longbridge Financial. The comparison becomes especially important when a homeowner is considering whether to replace an existing mortgage or preserve it while accessing additional equity.
Finance of America has offered proprietary reverse mortgage structures, including HomeSafe options, while Longbridge offers proprietary programs such as Platinum. The appropriate comparison depends on the current guidelines for the specific product and borrower.
Key questions include whether the program requires the existing first mortgage to be paid off, whether a second-lien structure is available, how the property is valued, how assets and income are evaluated, and what amount of equity may be accessible.
See Which California Jumbo Reverse Mortgage Options May Fit
Give us a few basic details about your property, mortgage, age, and financial profile. We can use that information to help explore a preliminary reverse mortgage scenario.
Confidential • No SSN Required • No Credit Inquiry at This Stage
See My Potential Equity Options →
How Much Could You Borrow With a California Jumbo Reverse Mortgage?
There is no single loan-to-value percentage or dollar amount that applies to every California jumbo reverse mortgage. Available proceeds can depend on:
Borrower age and, where applicable, the age of a co-borrower.
Current property value and the lender's appraisal.
Existing mortgage and other liens.
Interest rates and current program margins.
Property type, location, and condition.
Income, assets, credit, and financial assessment.
The specific proprietary program selected.
Want a Quick Estimate?
Use the S.O.S. Loans reverse mortgage calculator to estimate potential proceeds in seconds. For a more detailed scenario review, use the confidential inquiry option below.
Open Reverse Mortgage Calculator →
Illustrative only: A published maximum loan amount does not mean every borrower with a similarly valued property will qualify for that amount. Actual proceeds require a property-specific and borrower-specific analysis.
How Financial Assessment Works for a California Jumbo Reverse Mortgage
Financial assessment is an important part of proprietary reverse mortgage underwriting. Unlike a conventional forward mortgage, the analysis is not necessarily based on a simple debt-to-income ratio alone.
Depending on the program, the lender may evaluate income, retirement distributions, liquid assets, credit history, property expenses, taxes, insurance, and other recurring obligations.
Available income and qualifying assets are evaluated against the borrower's required expenses and financial obligations under the applicable program guidelines.
For asset-rich California homeowners, documentation can therefore be particularly important. Retirement accounts, investment assets, trust income, pensions, Social Security, and other qualifying resources may be treated differently depending on the lender.
California Property and Underwriting Considerations
California's higher-value real estate markets create some unique underwriting considerations. Property value alone does not determine whether a jumbo reverse mortgage is available.
Orange County and Coastal California
High-value properties in Newport Beach, Laguna Beach, Irvine, Dana Point, and surrounding Orange County communities may require careful appraisal review because property values can vary significantly between neighborhoods and individual properties.
Los Angeles and Southern California
Luxury homes in Los Angeles County and surrounding markets can involve unusual property characteristics, large lots, custom construction, hillside locations, condominiums, trusts, or other factors that require careful review.
Bay Area and Northern California
Homeowners in high-value Northern California communities may have substantial wealth concentrated in real estate and investment assets. Documentation and financial assessment can therefore be an important part of the process.
For additional background, see our California Jumbo Reverse Mortgage Guide .
Trusts, Title and Estate Planning Considerations
Many California homeowners with significant real estate holdings own their property through a revocable living trust or another estate-planning structure. Whether a particular trust arrangement is acceptable depends on the applicable lender's current requirements and legal review.
Before changing title, transferring ownership, or modifying an existing trust, homeowners should consult their estate-planning attorney and tax professional. A reverse mortgage professional can coordinate with those advisors regarding the financing structure, but should not replace individualized legal or tax advice.
HomeSafe Second vs. Traditional Jumbo Reverse Mortgages
One strategy that can be particularly relevant for some California homeowners is a proprietary reverse mortgage structured as a second lien. The objective is to access additional home equity while preserving an existing first mortgage.
This can be worth evaluating when a homeowner has an existing first mortgage with a relatively low interest rate and does not want to replace it with a new first-lien reverse mortgage.
Why a Second-Lien Structure May Matter
A qualifying second-lien reverse mortgage may allow a homeowner to retain an existing first mortgage while accessing additional equity. Availability, maximum proceeds, combined loan-to-value requirements, and payment obligations are subject to the applicable program's current guidelines.
Learn more about HomeSafe Second in California and how a second-lien strategy differs from a traditional first-lien reverse mortgage.
California Jumbo Reverse Mortgage Examples
Example 1: Preserving an Existing Low-Rate Mortgage
Consider a California homeowner with a high-value property and an existing first mortgage carrying a comparatively low interest rate. If the homeowner needs additional liquidity, a second-lien proprietary reverse mortgage may be worth evaluating if the borrower, property, and existing mortgage satisfy current program requirements.
The potential advantage is structural: rather than automatically replacing the first mortgage, the homeowner may be able to evaluate a second-lien solution. Whether that is financially preferable depends on the available proceeds, costs, interest rates, and the borrower's goals.
Example 2: Significant Assets but Limited Monthly Income
Consider a retired California homeowner with substantial equity and investment assets but relatively modest monthly income. Depending on the program, qualifying assets may be considered as part of the lender's financial assessment.
The exact treatment of retirement and investment assets varies by lender. Comparing programs can therefore be important when one underwriting structure does not produce the desired result.
Looking at Southern California?
If your property is in Orange County, Los Angeles, San Diego, or another Southern California market, see our guide to jumbo reverse mortgage lenders in Southern California .
Frequently Asked Questions About California Jumbo Reverse Mortgages
What is a jumbo reverse mortgage in California?
A California jumbo reverse mortgage is a proprietary reverse mortgage designed for qualifying homeowners whose property value or borrowing needs may exceed the limits of traditional FHA-insured HECM financing.
How does Mutual of Omaha compare with Longbridge Financial?
Both offer proprietary reverse mortgage options, but their current eligibility requirements, property guidelines, available proceeds, pricing, and underwriting criteria can differ. The better fit depends on the specific borrower and property.
How much can you borrow with a California jumbo reverse mortgage?
Potential proceeds depend on factors including borrower age, property value, existing liens, interest rates, property type, financial assessment, and the specific proprietary program. A published maximum loan amount is not a guarantee that every borrower will qualify for that amount.
Can a jumbo reverse mortgage be used on a high-value California home?
Potentially. Proprietary reverse mortgage programs are designed to accommodate higher-value properties, but eligible property types and property-value requirements vary by program.
What is the difference between a jumbo reverse mortgage and a HECM?
A HECM is an FHA-insured reverse mortgage subject to federal program requirements and applicable lending limits. A proprietary jumbo reverse mortgage is privately offered and may accommodate higher-value properties or larger borrowing needs, subject to the applicable lender's requirements.
Can a reverse mortgage preserve an existing low-rate first mortgage?
Some proprietary second-lien structures are designed to allow a qualifying homeowner to retain an existing first mortgage while accessing additional equity. Availability and maximum proceeds depend on the current program guidelines.
Does a jumbo reverse mortgage require monthly mortgage payments?
Reverse mortgage structures generally do not require the same monthly principal-and-interest payments as a conventional forward mortgage, but borrowers remain responsible for obligations such as property taxes, homeowners insurance, property maintenance, occupancy requirements, and other obligations under the loan documents. Second-lien structures can have different payment requirements and should be reviewed carefully.
Is a California jumbo reverse mortgage right for everyone?
No. The appropriate financing depends on the homeowner's age, property, existing debt, financial profile, objectives, costs, and the requirements of available programs.
Get Your Preliminary Scenario
Compare Your California Jumbo Reverse Mortgage Options
Different proprietary reverse mortgage programs can produce different results for the same California property and borrower. Give S.O.S. Loans a few basic details so we can help explore which available options may be worth evaluating.
Confidential • No SSN Required • No Credit Inquiry at This Stage • No Obligation
See My Potential Equity Options →
Which California Jumbo Reverse Mortgage Is Right for You?
There is no single proprietary reverse mortgage that is best for every California homeowner. Mutual of Omaha, Longbridge Financial, Finance of America, and other providers may have different eligibility requirements, property guidelines, lien structures, costs, and underwriting criteria.
For a homeowner with a high-value California property, the most appropriate option depends on the individual scenario, including age, property value, existing mortgage balance, property type, available equity, financial assessment, and the homeowner's goals.
S.O.S. Loans can help qualified California homeowners compare available jumbo and proprietary reverse mortgage structures and determine which programs may be worth evaluating. All loan scenarios remain subject to applicable lender guidelines, property valuation, financial assessment, and underwriting.
Not Ready to Submit Your Scenario?
Start with the S.O.S. Loans reverse mortgage calculator and get an estimate of potential proceeds.
Calculate Potential Proceeds →

Frank Stiebel specializes in California reverse mortgage financing, including proprietary and jumbo reverse mortgage programs for qualifying homeowners with higher-value properties. S.O.S. Loans helps homeowners compare available financing options while recognizing that final eligibility, terms, and approval are determined by the applicable lender and program guidelines.