Venmo Personal Loans | Can You Borrow From Venmo? (+ Approved alternatives)
- Venmo Personal Loan
Can you borrow money from Venmo? The definitive answer is no. Venmo does not provide direct personal loans, emergency installment cash, or a built-in borrowing feature equivalent to “Cash App Borrow.” While Venmo provides a consumer credit card issued by Synchrony Bank and merchant split-pay checkout (“Pay in 4”), it remains a peer-to-peer (P2P) payment network rather than a direct cash installment lender.
If you are facing an urgent financial emergency, consolidating debt, or needing fast liquid funds deposited into your checking account or digital wallet, you have viable alternatives. Below is the complete 2026 breakdown of how cash advance apps link to Venmo, why predatory “Venmo payday loans” should be avoided, and how California residents can secure $5,000 to $50,000 in fully amortized direct installment loans through a licensed California direct lender.
Licensed California Direct Lender Need $5,000 to $50,000 in Fast Direct Cash?Skip the $50 app limits, recurring subscription fees, and 400% payday APRs. S.O.S. Loans provides fast California personal loans and auto equity capital deposited directly into your bank account. California Financing Law License #603K478 | NMLS #2222125 | Checking terms will not affect your credit score |
Does Venmo Have a Borrow Feature or Offer Loans?
With over 85 million active accounts, millions search monthly for terms like “how to borrow money from Venmo” and “does Venmo offer loans.” However, Venmo does not operate an internal installment lending arm.
The confusion usually arises from three distinct financial features branded under Venmo and its parent company, PayPal:
Venmo Credit Card (Synchrony Bank): A physical Visa card linked to your profile. While it permits ATM cash advances, these withdrawals trigger immediate cash-advance transaction fees (typically $10 or 5%), immediate interest accrual at APRs exceeding 29%–33%, and a low cash-advance limit that is only a small fraction of your total credit line.
Venmo “Pay in 4” Split Checkout: A point-of-sale retail option enabling buyers to split eligible merchant purchases ($30 to $1,500) into four interest-free bi-weekly payments. Crucially, this cannot be withdrawn as cash, sent to friends, or deposited into a bank account.
Venmo Debit Card Direct Deposit: Lets users route their employer payroll to receive checks up to two days early. While helpful for cash-flow timing, it is strictly an advance on money you have already earned—not a loan or line of credit.
Can You Borrow From Venmo Like Cash App?
A frequent search query is “can you borrow from Venmo like Cash App?” Cash App offers a pilot feature called “Cash App Borrow,” allowing select eligible users to take short-term micro-loans between $20 and $200 (up to $500 for high-volume accounts) with a flat 5% fee repaid over four weeks.
Venmo has no equivalent tool. If an external website or social media post claims to unlock a “secret Venmo borrow button” or asks for your login credentials to process a “Venmo loan application,” it is an active phishing scam. Legitimate lenders will never ask for your Venmo password or authentication PIN.
Cash Advance Apps That Work With Venmo
Because Venmo does not extend credit, consumers needing micro-advances ($50 to $500) turn to third-party cash advance applications. While these apps cannot integrate directly into Venmo's backend, you can route advances to Venmo by connecting your Venmo Mastercard Debit Card or your linked checking account:
How Third-Party Apps Connect to Your Venmo Balance:
EarnIn: Tracks hourly or salaried hours worked and lets eligible W-2 workers access up to $100/day ($750 per pay cycle). By setting your linked checking account or debit card as the disbursement destination, funds can be transferred into your Venmo balance.
Dave (ExtraCash™): Delivers micro-advances up to $500. Regular transfers take 2–3 business days; instant transfers require an express fee of $3 to $15 depending on the advance amount.
Brigit: Extends instant advances from $50 to $250 to prevent overdrafts. Requires an active checking account and a mandatory monthly membership fee ($8.99 to $14.99/month).
MoneyLion (Instacash): Offers zero-APR advances up to $500 based on recurring direct deposits, which can be disbursed to an external account connected to Venmo.
Cleo & Beem: AI-driven financial assistants offering micro-advances between $20 and $250. Both require recurring payroll deposits and charge monthly subscription tiers for expedited cash delivery.
Comparison: Venmo vs. Cash Advance Apps vs. S.O.S. California Direct Loans
When you face substantial financial obligations—such as vehicle repairs, high-interest credit card consolidation, medical bills, or tax payments—micro-advance apps falling under $500 do not solve the underlying shortfall.
Lending Parameter | Venmo App | Cash Advance Apps (EarnIn, Dave) | S.O.S. Loans (Licensed CA Lender) |
|---|---|---|---|
Maximum Available Funds | $0 (No direct personal loans) | $50 – $500 (Strict ceiling) | $5,000 to $50,000 |
Disbursement Method | N/A | App balance or card transfer | Direct ACH deposit or wire into bank |
Repayment Schedule | N/A | Full deduction on next payday (7–14 days) | Predictable fixed monthly terms (24–60 mos) |
Monthly Cost Structure | None | $1–$15/mo subscriptions + tip requests | Simple interest rate, zero subscription charges |
Credit Bureau Reporting | Credit card only | No positive reporting to credit bureaus | Reports on-time monthly payments |
Regulatory Oversight | Federal banking partners (Visa/FDIC) | Operate outside state lending statutes | Licensed under California Financing Law (CFL) |
The Hidden Trap: “Payday Loans That Accept Venmo Online”
When borrowers find out Venmo has no loan feature, they often search for “payday loans that accept Venmo” or “instant online loans that deposit to Venmo.” This search carries significant financial risks:
Astronomical APRs: Unregulated online payday lenders commonly carry effective annual interest rates ranging from 350% to over 600%. A $400 advance can quickly cost $150+ in fees every two weeks.
The Payday Rollover Cycle: Because payday lenders demand full balloon repayment on your next paycheck, borrowers regularly find themselves short on basic living expenses two days later, forcing them into a cycle of repeated re-borrowing.
Bank Scraping Vulnerability: Many offshore payday operations require login credentials to your checking account via third-party scrapers, resulting in unexpected automated clearing house (ACH) sweep attempts that trigger cascading bank overdraft charges.
By contrast, a licensed California installment loan spreads your payments across predictable, amortized monthly installments. You know your exact payoff date, interest rate, and monthly obligation from day one.
California Direct Lending Solutions: Finding the Right Fit
Rather than relying on micro-advances or risking predatory payday traps, California residents can explore two core direct-lender financing programs backed by strict state compliance:
Unsecured Financing Zero Collateral California W-2 Personal Loans$5,000 – $50,000 Designed for salaried and hourly California professionals seeking substantial liquidity for debt consolidation, home improvements, or unexpected bills.
| Asset-Backed Solution Keep Driving Your Car Auto & Vehicle Title Equity Loans$2,510 – $50,000 Leverage the built-in equity in your paid-off or near paid-off vehicle, RV, EV, or motorcycle without surrendering your vehicle or keys.
|
How to Transfer Personal Loan Funds to Your Venmo Account
If you manage your everyday budget, rent, or bill splits through Venmo, you can easily use funds from an approved direct loan inside your Venmo ecosystem:
Direct ACH Deposit: Your loan proceeds ($5,000–$50,000) are wired or deposited via direct ACH into your primary checking account.
Link Your Checking Account: In the Venmo app, go to Settings → Payment Methods → Add bank or card, and select your bank.
Add Funds Instantly: Tap your profile balance, choose “Add Money,” and transfer the exact dollar amount needed into your digital Venmo wallet for immediate P2P spending or bill settlement.
Frequently Asked Questions (FAQ)
Can you borrow money from Venmo instantly?
No. Venmo has no instant borrowing service. To receive instant emergency cash, you must use a third-party cash advance app (like EarnIn or Dave) linked to your Venmo debit card or apply for an express direct installment loan with a licensed direct lender.
Does Venmo do loans for bad credit?
Because Venmo does not issue personal loans, there are no “Venmo bad credit loans.” Borrowers with low credit scores or limited credit history who need real capital often turn to California Auto Title Equity Loans ($2,510–$50,000), where approval is anchored by the appraised equity in your vehicle rather than traditional FICO benchmarks.
Does Venmo work with credit unions?
Yes. You can link any standard federal or state-chartered credit union checking account to your Venmo wallet using your credit union routing number and account number, or via instant verification through Plaid.
What are the requirements for a California direct personal loan?
To qualify for an unsecured personal loan with S.O.S. Loans ($5,000 to $50,000), applicants must be California residents, have verifiable W-2 employment with at least $6,000/month in gross income, possess an active checking account, and meet standard debt-to-income (DTI) underwriting guidelines.
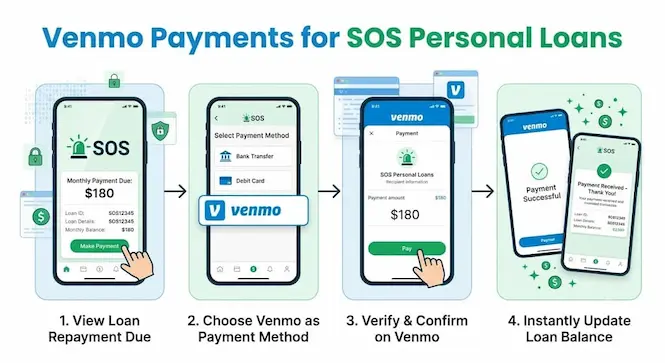
Active S.O.S. Loans Borrowers: How to Submit Payments via Venmo
If you currently have an open personal loan or auto equity loan with S.O.S. Loans, you can submit scheduled monthly installments directly via Venmo:
Official Business Handle: @SOSLoans on Venmo
Memo Requirement: Always include your S.O.S. Loan Account Number in the payment notes to ensure immediate, accurate ledger credit.
Get True California Capital Without App LimitsAccess $5,000 to $50,000 in fast, fully transparent funding backed by a licensed California direct lender. Simple application, fast approvals, and no prepayment penalties. Start Your 2-Minute Pre-Qualification → S.O.S. Loans, Inc. | California Financing Law (CFL) License #603F428 | NMLS ID: 2222125 |